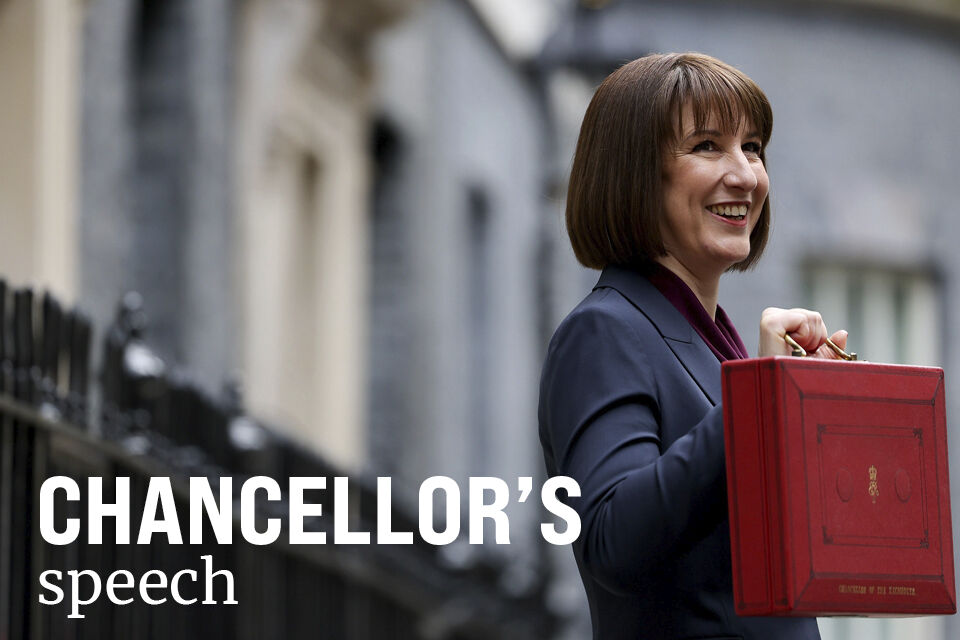
The Spring Statement has arrived, being delivered to the House of Commons on the 3rd of March 2026 by Chancellor Rachel Reeves. There were no big surprises or major adjustments from the changes discussed from the larger-than-usual Autumn Statement with the focus this time being on the fiscal performance of the government and economy, however there are confirmations of previous policy announcements to consider for the 2026/27 tax year.
Changes announced since Autumn
Pubs and music venues are set to see their business rates cut, as announced in January 2026. This constitutes a 15% discount on their business rates, along with a two-year real-terms freeze. This 15% discount will be applied after any other reliefs claimed such as Supporting Small Businesses relief.
The £1m Agricultural and Business Property Reliefs threshold will rise to £2.5m. This new measure was initially announced back in the Autumn statement at rate of £1m, however after public feedback, the government announced a rise to £2.5m in December 2025 and it is set to become policy from 6th April 2026. This will allow 100% IHT relief on transfers between spouses or partners up to a value of £2.5m on agricultural and business property, with a rate of 50% relief applying thereafter. A reduced rate of 20% IHT is to be charged on qualifying assets, with a 10-year payment instalment plan available to settle the bill.
Fuel duty, which was previously frozen in the Autumn statement, is now set to rise for the first time since 2011 having been frozen by successive governments. The 5p cut currently in force means that the current rate is £0.5295 per litre, however this 5p cut will be gradually rolled back starting from 1st September 2026, and the duty will revert to it’s former rate of £0.5795 per litre from March 2027.
Coming into force from April 2026
There are of course a number of tax changes announced in the Autumn about to come into force from 6th April 2026, so here’s a quick refresh on a few of the key points:
- Dividend tax rates to increase 2% on the basic and higher rate.
- Rental and savings income tax rates to increase 2% across the board
- Reduction in the main writing-down allowance of 18% to 14% for incorporated and unincorporated businesses.
- Increases in the National Living Wage:
- 21 and over – from £12.21 to £12.71
- 18 – 20 – from £10 to 10.85
- 16 to 17 and Apprentices – from £7.55 to £8
If you missed the Autumn Statement and want to read about the new changes in a bit more detail, you can find the full announcement here.
Topics
Archive
- 2026
- June 2026 (1)
- April 2026 (1)
- March 2026 (1)
- February 2026 (1)
- 2025
- December 2025 (1)
- August 2025 (1)
- July 2025 (1)
- June 2025 (1)
- May 2025 (1)
- March 2025 (2)
- February 2025 (1)
- January 2025 (1)